Heat Maps: Difference between revisions
| (10 intermediate revisions by the same user not shown) | |||
| Line 2: | Line 2: | ||
You are here: Governance Gaps; Governance Gaps; '''--''' '''Heat Maps''' | You are here: Governance Gaps; Governance Gaps; '''--''' '''Heat Maps''' | ||
If unfamiliar with the concept of Heat Maps, you may want to review the section titled [[Heat Maps#Heat Map? What's that?|Heat Map? What's that?]] and then return to the top of this webpage. | |||
After learning about Governance Gaps additional supporting details are available from the following web pages: | After learning about Governance Gaps additional supporting details are available from the following web pages: | ||
| Line 7: | Line 9: | ||
* Governance Gaps; Governance Gaps; --[[Interesting Takeaways]] | * Governance Gaps; Governance Gaps; --[[Interesting Takeaways]] | ||
=== Special | === Special Findings === | ||
This section identifies governance gaps that were identified as problematic. However, these findings were not derived from a comparison of all attributes in the conventional sense. | |||
* Principle #2 - Exercise Oversight Responsibility was identified as a priority because of a lack of oversight. There was no way to assess oversight if no oversight was being implemented. | |||
* Documentation Requirements was identified as a priority. Documentation requirements stated in only seven of 196 Green Book Attributes and weaknesses were identified in all seven Attributes. | |||
Heat Map Findings will be presented after the Special Findings. | |||
==== Top Priority - Principle 2 - Exercise Oversight Responsibility ==== | ==== Top Priority - Principle 2 - Exercise Oversight Responsibility ==== | ||
'''Principle 2 - Exercise Oversight Responsibility''' was an unexpected surprise! | |||
The Green Book summary of Principle #2 is stated in the following: | The Green Book summary of Principle #2 is stated in the following: | ||
'''[[2.01|Attribute 2.01]]''' The oversight body should oversee the entity's internal control system. | '''[[2.01|Attribute 2.01]]''' The oversight body should oversee the entity's internal control system. | ||
| Line 20: | Line 26: | ||
* Oversight for the Internal Control System | * Oversight for the Internal Control System | ||
* Input for Remediation of Deficiencies | * Input for Remediation of Deficiencies | ||
The trending of Maricopa County poor governance practices and behaviors began with the assumption that problematic internal controls would be shown by a higher number of observations. Contrary to this assumption, Principle 2 - Exercise Oversight Responsibility stood out as a governance weakness because a surprisingly <u>low</u> number of oversight observations, not high numbers. The low numbers were NOT because of good oversight; the low numbers were because of an <u>absence of oversight.</u> There was no oversight in place to judge the performance of the oversight entity. In fact, in many cases Maricopa County consciously acted in ways to prevent oversight. | |||
The Maricopa County Board of Supervisors (MCBOS) should have been directly responsible for oversight of Maricopa County programs, processes and people. Instead, MCBOS blocked, stalled and litigated against the Arizona Senate that was trying to provide oversight in 2021 to election anomalies that occurred prior to, during and after the 2020 General Election. | The Maricopa County Board of Supervisors (MCBOS) should have been directly responsible for oversight of Maricopa County programs, processes and people. Instead, MCBOS blocked, stalled and litigated against the Arizona Senate that was trying to provide oversight in 2021 to election anomalies that occurred prior to, during and after the 2020 General Election. | ||
Read a section titled [[Interesting Takeaways#Who is Watching the Hen House|Who is watching the hen house?]] on the Interesting Takeaways webpage for a list of entities that should be performing oversight, but were blocked by the county, neglected their duty or actively prevented other entities from performing their oversight role. | Read a section titled [[Interesting Takeaways#Who is Watching the Hen House|Who is watching the hen house?]] on the [[Interesting Takeaways]] webpage for a list of entities that should be performing oversight, but were blocked by the county, neglected their duty or actively prevented other entities from performing their oversight role. | ||
Maricopa County's performance with Principle 2 - Exercise Oversight Responsibility is the '''weakest''' of all 17 Green Book Principles even though it's heat map rating was low. | Maricopa County's performance with Principle 2 - Exercise Oversight Responsibility is the '''weakest''' of all 17 Green Book Principles even though it's heat map rating was low. | ||
==== Second Priority - Documentation Requirements ==== | |||
The US GAO's Green Book has a special consideration for Documentation Requirements, which are as follows: | |||
Note: Bold font was emphasized by the US GAO, and underlined font was emphasized by ACV. | |||
OV2.10 <u>Documentation is a necessary part of an effective internal control system.</u> The level and nature of documentation may vary based on the size of the entity and the complexity of the processes it performs. Management exercises judgment in determining the extent or type of documentation that is needed. | |||
OV2.11 <u>Documentation is required for the effective design, implementation, and operating effectiveness of an entity's internal control system.</u> Management develops and maintains documentation of its internal control system. | |||
OV2.12 These requirements represent the minimum level of documentation in an entity's internal control system. Management exercises judgment in determining what additional documentation may be necessary for an effective internal control system. If management identifies deficiencies in achieving these documentation requirements, the effect of the identified deficiencies is considered as part of management's summary determination of whether the related principle is designed, implemented, and operating effectively. | |||
OV2.13 Minimum documentation requirements are identified throughout the Green Book with a symbol and the wording "'''[documentation requirement]'''" following the narrative. The minimum documentation requirements are also summarized in [https://guides.gaoinnovations.gov/greenbook/2025/appendix-i-requirements/ appendix I]. | |||
Maricopa County has repeatedly stated they are in compliance with the documentation requirements as stated in the law as a reason for not delivering documentation to oversight or the public. | |||
The United States Government Accountability Office states documentation is required for internal controls or good governance! | |||
OV2.13 describes the minimum documentation requirements, which are stated in the Green Book as an Attribute. Seven Attributes specify Documentation Requirements, which were plotted on a heat map (see [[Heat Maps#Heat Map of Documentation Requirements|Heat Map of Documentation Requirements]], below). | |||
Governance weaknesses were identified in six of the seven Attributes that specified Documentation Requirements. The low score for documentation of change assessment process, Attribute 9.05, was scored low because of the number of observations in that area, not because of strengths. | |||
Jamie's Public Records Request was seeking Maricopa County contracts with entities that support their implementation of Elections. Maricopa County delivered the Runbeck. The contract was changed after the original approval. However, [[Interesting Takeaways#Runbeck Contract Changes were not Approved, Justified or Explained|Runbeck Contract Changes were not Approved, Justified or Explained]] as described on the [[Interesting Takeaways]] webpage. | |||
The Arizona Superior Court for Maricopa County ruled in favor of the County in Jamie's complaint against the county for not fulfilling her Public Records Request. The legal team's primary argument is the county is under no obligation to create records unless required by law. This may prevail in court. However, this is an example of poor governance. See the section titled [[Interesting Takeaways#Can you see a pattern?|Can you see a pattern?]] from the [[Interesting Takeaways]] webpage. | |||
=== Heat Map Findings === | === Heat Map Findings === | ||
This section identifies the top governance issues identified from the trending of Maricopa County internal control weaknesses identified from Jamie's personal observations or publicly available information. | This section identifies the top governance issues identified from the trending of Maricopa County internal control weaknesses identified from Jamie's personal observations or publicly available information. | ||
==== | ==== Third Priority - Principle 1 - Demonstrate Commitment to Integrity and Ethical Values ==== | ||
The Green Book summary of Principle #1 is stated in the following: | The Green Book summary of Principle #1 is stated in the following: | ||
'''[[1.01|Attribute 1.01]]''' The oversight body and management should demonstrate a commitment to integrity and ethical values. | '''[[1.01|Attribute 1.01]]''' The oversight body and management should demonstrate a commitment to integrity and ethical values. | ||
| Line 53: | Line 84: | ||
Meanwhile, Maricopa County leaders and frontline employees willingly did not comply with written procedures according to the [https://www.azag.gov/sites/default/files/2025-06/2020_General_Election_Investigation_Summary.pdf 2020 General Election the Arizona Attorney General's Office 2020 General Election Investigation,] Allegation #2. Additional details are available from a section titled [[Interesting Takeaways#Procedures Violated with Unknown Consequences|Procedures Violated with Unknown Consequences]] from the [[Interesting Takeaways]] webpage. Violating procedures is unethical, but not against the law. In this case, five procedure violations may have potentially compromised thousands or tens of thousands of ballots. Those violating procedures may have felt that "If the people at the top can push the limits of ethical behavior, why can't we do the same?" | Meanwhile, Maricopa County leaders and frontline employees willingly did not comply with written procedures according to the [https://www.azag.gov/sites/default/files/2025-06/2020_General_Election_Investigation_Summary.pdf 2020 General Election the Arizona Attorney General's Office 2020 General Election Investigation,] Allegation #2. Additional details are available from a section titled [[Interesting Takeaways#Procedures Violated with Unknown Consequences|Procedures Violated with Unknown Consequences]] from the [[Interesting Takeaways]] webpage. Violating procedures is unethical, but not against the law. In this case, five procedure violations may have potentially compromised thousands or tens of thousands of ballots. Those violating procedures may have felt that "If the people at the top can push the limits of ethical behavior, why can't we do the same?" | ||
==== | ===== Lack of Oversight ===== | ||
Intuitively, ACV saw clear link between ineffective organizational oversight and organizations prone to unethical behaviors and integrity lapses. In ACV's first use of Artificial Intelligence (Google-based), ACV searched "What role does lack of organizational oversight lead to poor organizational ethics?" and received the following response: | |||
<nowiki>***</nowiki> | |||
Lack of organizational oversight significantly contributes to poor organizational ethics. Without effective oversight mechanisms, organizations may experience several detrimental effects: | |||
* Inconsistent Decision-Making: When oversight is weak, there are often no clear guidelines or processes for ethical decision-making. This can lead to reliance on personal judgment, resulting in varied responses to similar ethical dilemmas. | |||
* Increased Risk of Misconduct: Weak oversight can create an environment where unethical behavior goes unchecked. Employees may feel empowered to engage in unethical practices if they believe there will be no consequences. | |||
* Erosion of Accountability: A lack of oversight diminishes accountability at all levels. When individuals are not held responsible for their actions, it can foster a culture of impunity, further undermining ethical standards. | |||
* Failure to Address Ethical Issues: Without proper oversight, ethical concerns may not be identified or addressed in a timely manner. This can lead to a culture where ethical violations become normalized. | |||
<nowiki>***</nowiki> | |||
This AI response confirmed ACV's belief that a '''Lack of Effective Oversight was a higher priority than Ethical and Integrity Issues.''' Negative outcomes result from both. However, effective oversight is needed to improve ethical and integrity issues. Conversely, oversight is not made more effective from strong organizational ethics and integrity. | |||
* '''Principle 2 - Exercise Oversight Responsibility''' was ranked as our highest priority, even with a low heat map score. | |||
* '''Principle 1 - Demonstrate Commitment to Integrity and Ethical Values''' was ranked as our third priority. | |||
==== Fourth Priority - Principle #17 - Evaluate Issues and Remediate Deficiencies ==== | |||
The Green Book summary of Principle #17 is stated in the following: | The Green Book summary of Principle #17 is stated in the following: | ||
'''[[17.01|Attribute 17.01]]''' Management should remediate identified internal control deficiencies on a timely basis. | '''[[17.01|Attribute 17.01]]''' Management should remediate identified internal control deficiencies on a timely basis. | ||
| Line 63: | Line 113: | ||
Principle #17 - Evaluate Issues and Remediate Deficiencies was the second <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 38% of all possible observations of Green Book Attributes within Principle 17 were scored as weakness. | Principle #17 - Evaluate Issues and Remediate Deficiencies was the second <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 38% of all possible observations of Green Book Attributes within Principle 17 were scored as weakness. | ||
==== | |||
Finish this section!!!!! | |||
==== Fifth Priority - Principle #12 - Implement Control Activities (25%) ==== | |||
The Green Book summary of Principle #12 is stated in the following: | The Green Book summary of Principle #12 is stated in the following: | ||
'''[[12.01|Attribute 12.01]]''' Management should implement control activities through policies and procedures. | '''[[12.01|Attribute 12.01]]''' Management should implement control activities through policies and procedures. | ||
| Line 72: | Line 125: | ||
Principle #12 - Implement Control Activities was the third <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 25% of all possible observations of Green Book Attributes within Principle 12 were scored as weakness. | Principle #12 - Implement Control Activities was the third <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 25% of all possible observations of Green Book Attributes within Principle 12 were scored as weakness. | ||
Finish this section!!!!! | |||
==== | ==== Sixth Priority - Principle #8 - Assess Fraud, Improper Payments and Information (24%) ==== | ||
The Green Book summary of Principle #8 is stated in the following: | The Green Book summary of Principle #8 is stated in the following: | ||
'''[[8.01|Attribute 8.01]]''' Management should consider risks related to fraud, improper payments, and information security when identifying, analyzing, and responding to risks. | '''[[8.01|Attribute 8.01]]''' Management should consider risks related to fraud, improper payments, and information security when identifying, analyzing, and responding to risks. | ||
| Line 85: | Line 139: | ||
Principle #8 - Assess Fraud, Improper Payments and Information was the fourth <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 24% of all possible observations of Green Book Attributes within Principle 8 were scored as weakness. | Principle #8 - Assess Fraud, Improper Payments and Information was the fourth <u>weakest</u> Green Book Principle based on the Heat Maps, which plotted ACV's observations. 24% of all possible observations of Green Book Attributes within Principle 8 were scored as weakness. | ||
Finish this section!!!!! | |||
=== Heat Map? What's that? === | === Heat Map? What's that? === | ||
A heat map is a graphical representation of data. The Heat Map uses colors to visualize the magnitude specific data point within a collection of a much larger data set. This allows the reader to quickly identify high and low values, clusters, or patterns without scanning raw numbers in a table or spreadsheet. | A heat map is a graphical representation of data. The Heat Map uses colors to visualize the magnitude specific data point within a collection of a much larger data set. This allows the reader to quickly identify high and low values, clusters, or patterns without scanning raw numbers in a table or spreadsheet. | ||
| Line 189: | Line 225: | ||
* '''Principle #12 - Implement Control Activities''' (43%) | * '''Principle #12 - Implement Control Activities''' (43%) | ||
* '''Principle #8 - Assess Fraud, Improper Payments and Information''' (39%) | * '''Principle #8 - Assess Fraud, Improper Payments and Information''' (39%) | ||
=== | === Heat Map of Documentation Requirements === | ||
The US GAO's Standards for Internal Control in the Federal Government Appendix I specifies Documentation Requirements for effective implementation of internal controls. A separate Heat Map was prepared to illustrate Maricopa County's governance with respect to Documentation Requirements. | The US GAO's Standards for Internal Control in the Federal Government Appendix I specifies Documentation Requirements for effective implementation of internal controls. A separate Heat Map was prepared to illustrate Maricopa County's governance with respect to Documentation Requirements. | ||
[[File:Documentation Requirements.png]] | [[File:Documentation Requirements.png]] | ||
=== Disclaimer === | |||
The data collected and plotted on these heat maps was constrained data availability. | |||
* ACV's observations were <u>not</u> obtained from an internal structured organizational assessment., which would have theoretically had better internal documents and employee attitudes obtained from interviews. | |||
* ACV's observations were obtained from the best available data, which included Jamie's personal experience and publicly available information from the internet. | |||
Jamie's personal experience was perhaps the most accurate for scoring of an individual Green Book Attribute because the insight came from a clear understanding of the context and there were no biases introduced by third parties. However, Jamie's personal agenda limited the number of Attributes observed; some governance attributes were simply not observed. | |||
An [https://www.azag.gov/sites/default/files/2025-06/2020_General_Election_Investigation_Summary.pdf Arizona Attorney General's Office 2020 General Election Investigation] was the primary source of publicly available information used for this governance assessment. This report from the AG's Office was prepared to address the Arizona Senate's allegations of malicious or criminal behavior after Maricopa County refused to willingly cooperate with the Senate's oversight of election anomalies. In this case, there were biases introduced by the investigators; these were not first-hand observations. That said, the documented observations of professional investigators were considered credible. The AG's Office found no criminal wrongdoing. However, their explanation for election anomalies repeatedly used sloppiness or poor governance as the explanation for the election anomaly. In other words, '''Maricopa County's inadequate internal controls or noncompliance with appropriate internal controls caused the election anomalies.''' | |||
Latest revision as of 15:29, 3 October 2026
This page explains how the governance gaps were plotted on a Heat Map to identify the weakest areas of Maricopa County governance.
You are here: Governance Gaps; Governance Gaps; -- Heat Maps
If unfamiliar with the concept of Heat Maps, you may want to review the section titled Heat Map? What's that? and then return to the top of this webpage.
After learning about Governance Gaps additional supporting details are available from the following web pages:
- Governance Gaps; Governance Gaps; --Interesting Takeaways
Special Findings
This section identifies governance gaps that were identified as problematic. However, these findings were not derived from a comparison of all attributes in the conventional sense.
- Principle #2 - Exercise Oversight Responsibility was identified as a priority because of a lack of oversight. There was no way to assess oversight if no oversight was being implemented.
- Documentation Requirements was identified as a priority. Documentation requirements stated in only seven of 196 Green Book Attributes and weaknesses were identified in all seven Attributes.
Heat Map Findings will be presented after the Special Findings.
Top Priority - Principle 2 - Exercise Oversight Responsibility
Principle 2 - Exercise Oversight Responsibility was an unexpected surprise!
The Green Book summary of Principle #2 is stated in the following:
Attribute 2.01 The oversight body should oversee the entity's internal control system.
Attributes of this principle are grouped into one of the following categories:
- Oversight Structure
- Oversight for the Internal Control System
- Input for Remediation of Deficiencies
The trending of Maricopa County poor governance practices and behaviors began with the assumption that problematic internal controls would be shown by a higher number of observations. Contrary to this assumption, Principle 2 - Exercise Oversight Responsibility stood out as a governance weakness because a surprisingly low number of oversight observations, not high numbers. The low numbers were NOT because of good oversight; the low numbers were because of an absence of oversight. There was no oversight in place to judge the performance of the oversight entity. In fact, in many cases Maricopa County consciously acted in ways to prevent oversight.
The Maricopa County Board of Supervisors (MCBOS) should have been directly responsible for oversight of Maricopa County programs, processes and people. Instead, MCBOS blocked, stalled and litigated against the Arizona Senate that was trying to provide oversight in 2021 to election anomalies that occurred prior to, during and after the 2020 General Election.
Read a section titled Who is watching the hen house? on the Interesting Takeaways webpage for a list of entities that should be performing oversight, but were blocked by the county, neglected their duty or actively prevented other entities from performing their oversight role.
Maricopa County's performance with Principle 2 - Exercise Oversight Responsibility is the weakest of all 17 Green Book Principles even though it's heat map rating was low.
Second Priority - Documentation Requirements
The US GAO's Green Book has a special consideration for Documentation Requirements, which are as follows:
Note: Bold font was emphasized by the US GAO, and underlined font was emphasized by ACV.
OV2.10 Documentation is a necessary part of an effective internal control system. The level and nature of documentation may vary based on the size of the entity and the complexity of the processes it performs. Management exercises judgment in determining the extent or type of documentation that is needed.
OV2.11 Documentation is required for the effective design, implementation, and operating effectiveness of an entity's internal control system. Management develops and maintains documentation of its internal control system.
OV2.12 These requirements represent the minimum level of documentation in an entity's internal control system. Management exercises judgment in determining what additional documentation may be necessary for an effective internal control system. If management identifies deficiencies in achieving these documentation requirements, the effect of the identified deficiencies is considered as part of management's summary determination of whether the related principle is designed, implemented, and operating effectively.
OV2.13 Minimum documentation requirements are identified throughout the Green Book with a symbol and the wording "[documentation requirement]" following the narrative. The minimum documentation requirements are also summarized in appendix I.
Maricopa County has repeatedly stated they are in compliance with the documentation requirements as stated in the law as a reason for not delivering documentation to oversight or the public.
The United States Government Accountability Office states documentation is required for internal controls or good governance!
OV2.13 describes the minimum documentation requirements, which are stated in the Green Book as an Attribute. Seven Attributes specify Documentation Requirements, which were plotted on a heat map (see Heat Map of Documentation Requirements, below).
Governance weaknesses were identified in six of the seven Attributes that specified Documentation Requirements. The low score for documentation of change assessment process, Attribute 9.05, was scored low because of the number of observations in that area, not because of strengths.
Jamie's Public Records Request was seeking Maricopa County contracts with entities that support their implementation of Elections. Maricopa County delivered the Runbeck. The contract was changed after the original approval. However, Runbeck Contract Changes were not Approved, Justified or Explained as described on the Interesting Takeaways webpage.
The Arizona Superior Court for Maricopa County ruled in favor of the County in Jamie's complaint against the county for not fulfilling her Public Records Request. The legal team's primary argument is the county is under no obligation to create records unless required by law. This may prevail in court. However, this is an example of poor governance. See the section titled Can you see a pattern? from the Interesting Takeaways webpage.
Heat Map Findings
This section identifies the top governance issues identified from the trending of Maricopa County internal control weaknesses identified from Jamie's personal observations or publicly available information.
Third Priority - Principle 1 - Demonstrate Commitment to Integrity and Ethical Values
The Green Book summary of Principle #1 is stated in the following:
Attribute 1.01 The oversight body and management should demonstrate a commitment to integrity and ethical values.
Attributes of this principle are grouped into one of the following categories:
- Tone at the Top
- Standards of Conduct
- Adherence to Standards of Conduct
Principle #1 - Demonstrate Commitment to Integrity and Ethical Values was the weakest Green Book Principle based on the Heat Maps, which plotted ACV's observations. 45% of all possible observations of Green Book Attributes within Principle 1 were scored as weakness.
Using the Law as a Shield for Accountability
A common theme to low scoring on Integrity and Ethical Values was recurring practices and behaviors of using existing laws as a shield by Maricopa leaders, front-line employees and legal team. In other words, they were accountable to no one as long as they were in compliance with the law.
Green Book Attribute 1.04 states (Emphasis added by ACV):
Attribute 1.04 The oversight body's and management's directives, attitudes, and behaviors reflect the integrity and ethical values expected throughout the entity. The oversight body and management reinforce the commitment to doing what is right, not just maintaining a minimum level of performance necessary to comply with applicable laws and regulations, so that these priorities are understood by all stakeholders, such as regulators, service organizations, employees, and the public.
The concept of hiding behind the law to avoid doing what is right is described in a section titled Well Aligned, but to the Wrong Purpose from the Interesting Takeaways webpage.
Wrong Tone Set at the Top
As Secretary of State, Kaite Hobbs oversaw her own election for Arizona Governor during the 2022 midterm election. She did not violate any law. However, her actions raised ethical issues. More importantly, she opened the door to poor ethical practices for those election workers that reported to her, directly or indirectly. If someone had low ethics, they would certainly be encouraged to push the limits if the person in charge was pushing the limits, especially if the "wrong" thing to do was still within the letter of the law (see above).
Attribute 1.03 The oversight body and management lead by an example that demonstrates the organization's values, philosophy, and operating style. The oversight body and management set the tone at the top and throughout the organization by their example, which is fundamental to an effective internal control system. In larger entities, the various layers of management in the organizational structure may also set the "tone in the middle." Although it is the oversight body and management's responsibility to set the tone at the top, other personnel throughout the entity play an important role in supporting the tone that permeates the organizational culture.
Meanwhile, Maricopa County leaders and frontline employees willingly did not comply with written procedures according to the 2020 General Election the Arizona Attorney General's Office 2020 General Election Investigation, Allegation #2. Additional details are available from a section titled Procedures Violated with Unknown Consequences from the Interesting Takeaways webpage. Violating procedures is unethical, but not against the law. In this case, five procedure violations may have potentially compromised thousands or tens of thousands of ballots. Those violating procedures may have felt that "If the people at the top can push the limits of ethical behavior, why can't we do the same?"
Lack of Oversight
Intuitively, ACV saw clear link between ineffective organizational oversight and organizations prone to unethical behaviors and integrity lapses. In ACV's first use of Artificial Intelligence (Google-based), ACV searched "What role does lack of organizational oversight lead to poor organizational ethics?" and received the following response:
***
Lack of organizational oversight significantly contributes to poor organizational ethics. Without effective oversight mechanisms, organizations may experience several detrimental effects:
- Inconsistent Decision-Making: When oversight is weak, there are often no clear guidelines or processes for ethical decision-making. This can lead to reliance on personal judgment, resulting in varied responses to similar ethical dilemmas.
- Increased Risk of Misconduct: Weak oversight can create an environment where unethical behavior goes unchecked. Employees may feel empowered to engage in unethical practices if they believe there will be no consequences.
- Erosion of Accountability: A lack of oversight diminishes accountability at all levels. When individuals are not held responsible for their actions, it can foster a culture of impunity, further undermining ethical standards.
- Failure to Address Ethical Issues: Without proper oversight, ethical concerns may not be identified or addressed in a timely manner. This can lead to a culture where ethical violations become normalized.
***
This AI response confirmed ACV's belief that a Lack of Effective Oversight was a higher priority than Ethical and Integrity Issues. Negative outcomes result from both. However, effective oversight is needed to improve ethical and integrity issues. Conversely, oversight is not made more effective from strong organizational ethics and integrity.
- Principle 2 - Exercise Oversight Responsibility was ranked as our highest priority, even with a low heat map score.
- Principle 1 - Demonstrate Commitment to Integrity and Ethical Values was ranked as our third priority.
Fourth Priority - Principle #17 - Evaluate Issues and Remediate Deficiencies
The Green Book summary of Principle #17 is stated in the following:
Attribute 17.01 Management should remediate identified internal control deficiencies on a timely basis.
Attributes of this principle are grouped into one of the following categories:
- Reporting of Issues
- Evaluation of Issues
- Corrective Actions
Principle #17 - Evaluate Issues and Remediate Deficiencies was the second weakest Green Book Principle based on the Heat Maps, which plotted ACV's observations. 38% of all possible observations of Green Book Attributes within Principle 17 were scored as weakness.
Finish this section!!!!!
Fifth Priority - Principle #12 - Implement Control Activities (25%)
The Green Book summary of Principle #12 is stated in the following:
Attribute 12.01 Management should implement control activities through policies and procedures.
Attributes of this principle are grouped into one of the following categories:
- Documentation of Control Activities Through Policies and Procedures
- Periodic Review of Control Activities
Principle #12 - Implement Control Activities was the third weakest Green Book Principle based on the Heat Maps, which plotted ACV's observations. 25% of all possible observations of Green Book Attributes within Principle 12 were scored as weakness.
Finish this section!!!!!
Sixth Priority - Principle #8 - Assess Fraud, Improper Payments and Information (24%)
The Green Book summary of Principle #8 is stated in the following:
Attribute 8.01 Management should consider risks related to fraud, improper payments, and information security when identifying, analyzing, and responding to risks.
Attributes of this principle are grouped into one of the following categories:
- Identify Risks Related to Fraud, Improper Payments, and Information Security
- Types of Fraud and Fraud Risk Factors
- Types of Improper Payments and Improper Payment Risk Factors
- Types of Information Security Risk and Information Security Risk Factors
- Analyze and Respond to Identified Risks
Principle #8 - Assess Fraud, Improper Payments and Information was the fourth weakest Green Book Principle based on the Heat Maps, which plotted ACV's observations. 24% of all possible observations of Green Book Attributes within Principle 8 were scored as weakness.
Finish this section!!!!!
Heat Map? What's that?
A heat map is a graphical representation of data. The Heat Map uses colors to visualize the magnitude specific data point within a collection of a much larger data set. This allows the reader to quickly identify high and low values, clusters, or patterns without scanning raw numbers in a table or spreadsheet.
Red colors represent a larger number of observations that found governance issues with the specific attribute. Attributes and Principles that are red or have reddish tones should be interpreted as organizational behaviors and practices that are in need of attention in terms of fulfilling the US GAO's Standards for Internal Control in the Federal Government.
Conversely Green colors represent a smaller number of observations that found governance issues with the specific attributes. Fewer observations may denote organizational alignment to the US GAO's Standards for Internal Control in the Federal Government. However, Green doesn't necessarily mean good governance; green colors or greenish tones may also mean there was insufficient observations in this area to make a judgement.
In summary, the heat maps shown in this section shows Green Book Attributes and Principles that suggest poor governance practices in red color or reddish tones. From a performance improvement perspective, reddish colors are worthy of management attention.
Attribute Portion of Heat Map
Attribute data is presented on the right side of the heat map as x.01 through x.23, where "x" denotes the Green Book Principle, and number to the right of the decimal point denotes the Attribute within the Principle (see below). This Attribute data is straightforward. For each relevant observation of a deviation from the stated attribute, a value of one was added to the cumulative score.. This is a one-for-one relationship. Larger number of observations are shown in red colors or reddish tones.
Colors were based on a comparison to all other Attributes within all Principles. Attributes were compared to Attributes.
Principle Portion of Heat Map
Some math was required to determine which Principles had the greater number of poor governance observations because of a wide range in the number attributes per Principle. For example, Principle #10 had 23 attributes while Principle #12 only had 5 Attributes. A straightforward numerical comparison would be invalid.
For Green Book Principles on the left side of the heat map, a weighting factor was used to normalize the observations for a fairer comparison. A percentage of actual observations to potential observations was determined for each of the 17 Green Book Principles.
All Green Book Principles weighting factors (%) were compared to other Principles, not Attributes. As with Attributes, Green colors do not necessarily denote good governance for the Principles; green colors may have occurred because the Attributes within a Principle were simply not observed.
Heat Map from All Observations

Based on observations, the Green Book Principles with the weakest governance performance are as follows:
- Principle #1 - Demonstrate Commitment to Integrity and Ethical Values (45%)
- Principle #17 - Evaluate Issues and Remediate Deficiencies (38%)
- Principle #12 - Implement Control Activities (25%)
- Principle #8 - Assess Fraud, Improper Payments and Information (24%)
Heat Map of Observations Taken from Jamie's Story
There were 11 events evaluated for potential governance gaps, which are deviations from the Green Book Standard. The Heat Map of Jamie's Stories was comprised of the following events:
- 2020: General Election Anomalies - Public View
- 2021: My Journey Begins
- November 2022: Ethical Issues with Katie Hobbs Overseeing Her Own Election
- May 15, 2025: Let’s Play Hot Potato
- June 25, 2025: Runbeck Contract Delivered
- November 20, 2025: Debbie Lesko Presentation
- March 12, 2026: Maricopa County Defense Briefing
- June 1, 2026: Judge's Decision
- June 8, 2026: Arizona State Ombudsman Replies
- June 9, 2026: Maricopa County Ombudsman Replies
- August 3, 2026: Submitted Complaint
Jamie's Story Heat Map Data 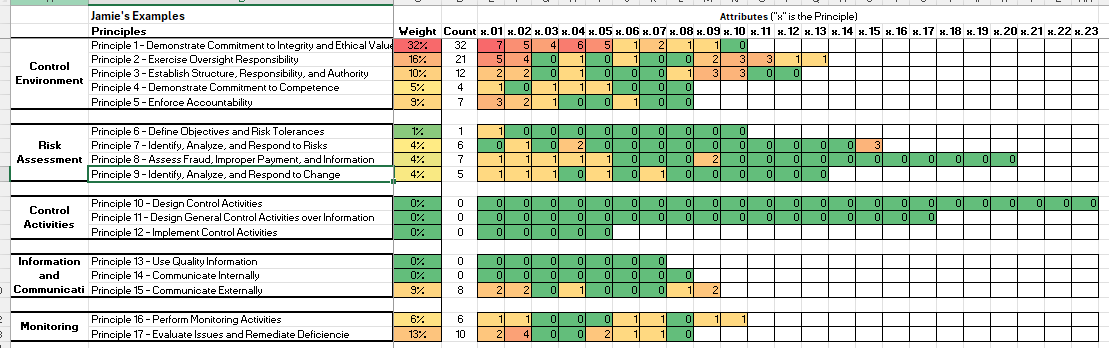

Interpretation of Jamie's Story Heat Map
- Principle #1 - Demonstrate Commitment to Integrity and Ethical Values (32%) stands out as dominant area of poor governance.
The next two items are as follows:
- Principle #2 - Exercise Oversight Responsibility (16%)
- Principle #17 - Evaluate Issues and Remediate Deficiencies (13%)
Heat Map of Observations Taken from Election Anomalies
There were 14 events evaluated for potential governance gaps, which are deviations from the Green Book Standard. The Heat Map of Election Anomalies was comprised of the following events:
- AZ AG's Investigation: Allegation #1 - Signature Verification
- AZ AG's Investigation: Allegation #2- Drop Box Collection
- AZ AG's Investigation: Allegation #3- Election Management System (EMS): Sub-allegation #1 - Data Purged
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #2 - Election Files Deleted
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #3 - Corrupt Ballot Images
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #4 - Missing Ballot Images
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #5 - Failure to follow basic Cyber Security practices
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #6 - Subpoenaed Equipment Not Provided
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #7 - Anonymous Logins
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #8 - Dual Boot System Discovered
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #9 - Operating System Logs Not Preserved
- AZ AG's Investigation: Allegation #3 - EMS: Sub-allegation #10 - Internet Connection to the EMS
- AZ AG's Investigation: Allegation #4 - Maricopa County Board of Supervisors did not Provide for Audit
- Maricopa County Assistant Director email Suspends Sharpie Markers and then directs there use on Election Day
Election Anomalies Heat Map Data

Interpretation of Election Anomaly Heat Map
The weakest areas of governance were with the following principles:
- Principle #1 - Demonstrate Commitment to Integrity and Ethical Values (54%)
- Principle #17 - Evaluate Issues and Remediate Deficiencies (54%)
- Principle #12 - Implement Control Activities (43%)
- Principle #8 - Assess Fraud, Improper Payments and Information (39%)
Heat Map of Documentation Requirements
The US GAO's Standards for Internal Control in the Federal Government Appendix I specifies Documentation Requirements for effective implementation of internal controls. A separate Heat Map was prepared to illustrate Maricopa County's governance with respect to Documentation Requirements.

Disclaimer
The data collected and plotted on these heat maps was constrained data availability.
- ACV's observations were not obtained from an internal structured organizational assessment., which would have theoretically had better internal documents and employee attitudes obtained from interviews.
- ACV's observations were obtained from the best available data, which included Jamie's personal experience and publicly available information from the internet.
Jamie's personal experience was perhaps the most accurate for scoring of an individual Green Book Attribute because the insight came from a clear understanding of the context and there were no biases introduced by third parties. However, Jamie's personal agenda limited the number of Attributes observed; some governance attributes were simply not observed.
An Arizona Attorney General's Office 2020 General Election Investigation was the primary source of publicly available information used for this governance assessment. This report from the AG's Office was prepared to address the Arizona Senate's allegations of malicious or criminal behavior after Maricopa County refused to willingly cooperate with the Senate's oversight of election anomalies. In this case, there were biases introduced by the investigators; these were not first-hand observations. That said, the documented observations of professional investigators were considered credible. The AG's Office found no criminal wrongdoing. However, their explanation for election anomalies repeatedly used sloppiness or poor governance as the explanation for the election anomaly. In other words, Maricopa County's inadequate internal controls or noncompliance with appropriate internal controls caused the election anomalies.